The stock market continues to surprise observers, prompting familiar anxieties as valuations reach historic highs. When markets crash, investors panic over shrinking retirement portfolios. However, even during periods of record-breaking growth, apprehension lingers. Investors worry that unprecedented valuations signal an inevitable, catastrophic downturn, particularly when a market boom is fueled by the frenzied momentum of the artificial intelligence sector.
For those blissfully detached from the daily financial drama, retirement and daily life continue uninterrupted. Yet, the broader conversation around the current investment cycle remains dominated by fear. Market participants frequently draw parallels to the early-2000s dot-com boom, warning that the current mania is moving too fast and reaching too high. This sentiment resonates deeply with veterans of past financial cycles, including internet financial commentators who navigated the dot-com era’s explosive growth and subsequent crash, which threatened early retirement plans and citizenship applications alike.

As questions mount regarding the sustainability of the current market cycle, discussions have moved from digital forums to live stages, including presentations at Camp FI Midwest and upcoming appearances at the Bogleheads conference. These sessions examine whether current economic anxiety is truly justified or merely a recurring symptom of human psychology when facing technological revolutions.
Will the AI Bubble Ruin our Retirement?
Reaching milestones like two decades of formal retirement provides a certain level of comfort with market volatility. Yet, fundamental questions from peers persist. Friends and acquaintances frequently ask how retirees can remain comfortable and sleep soundly given global uncertainties, political volatility, persistent inflation, escalating national debt, and international conflicts.

Remarkably, these exact concerns are not new. Similar anxieties dominated public discourse twenty years ago in 2006. During that era, the public wrestled with polarizing political leaders, ongoing conflicts in the Middle East, escalating national debt, and inflation concerns. Back then, overvalued asset prices were attributed to an inflating housing bubble rather than an artificial intelligence boom. Similarly, public anxiety centered on the outsourcing of domestic jobs to India and China rather than automation driven by algorithms.
Anxiety at the time also extended to "Peak Oil," a widespread debate predicting that rising fossil fuel consumption would inevitably outstrip dwindling global supplies. In reality, the subsequent two decades charted a completely different course.

Despite the catastrophic Great Financial Crisis of 2008—triggered by irrational exuberance over housing prices and complex financial leverage—long-term equity markets demonstrated resilience. Major market corrections, including the 2020 pandemic-induced downturn, appear modest when viewed across a multi-decade horizon. A hypothetical investment of one hundred thousand dollars made during those turbulent years would have expanded significantly over the subsequent two decades.
Simultaneously, broader global conditions improved remarkably by several measurable metrics. The proportion of the global population living in extreme poverty dropped from twenty percent in 2005 to eight percent over the following twenty years. Infant mortality rates were cut in half. Clean energy adoption surged, driven by a dramatic forty-fold decrease in the cost of solar panels, making solar generation a dominant force in new energy infrastructure. Concurrently, sales of pure electric vehicles rose from near zero to a substantial share of global automotive sales.

These historical realities challenge the premise that an uncertain future warrants persistent pessimism. Nevertheless, modern skeptics ask whether the current era is fundamentally different. Concerns persist regarding the unprecedented scale of the United States national debt, the immense valuation of the AI sector, or the theoretical risk of artificial general intelligence outstripping human control. Financial media routinely amplifies these fears, often overlooking a fundamental economic principle: true prosperity originates from productivity, not financial systems and stock market valuations.
The Core Driver of Prosperity: Productivity
Economic prosperity is rooted in productivity rather than the fluctuating numerical metrics displayed on computer screens within financial markets. The capitalist system is inherently volatile and prone to cyclical swings, but beneath these surface waves, human labor, ingenuity, and invention drive tangible progress.

An economy or a financial system is ultimately a human construct. If a financial system experiences a severe contraction, society retains the capacity to restructure its mechanisms and resume productive work, a pattern demonstrated successfully during the 2008 financial crisis and historical downturns preceding it. Societies retain the foundational tools required to enhance productivity, which directly influences living standards, economic growth, and the feasibility of early retirement.
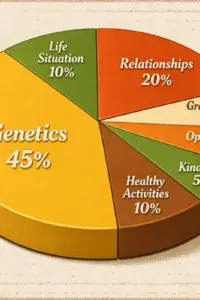
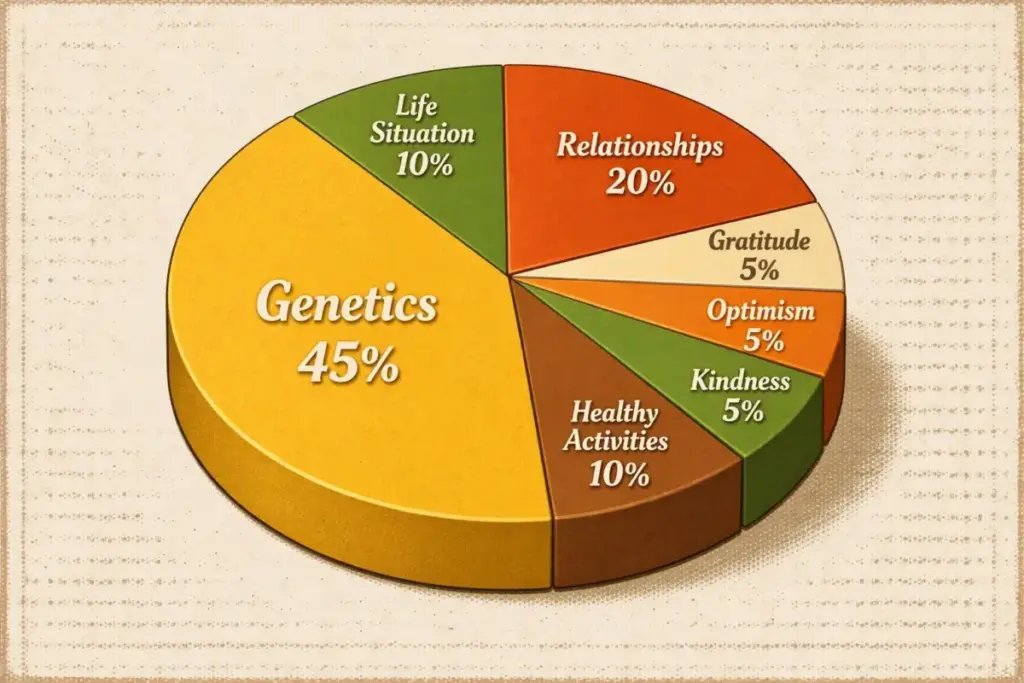
However, beyond productivity and material prosperity, human well-being plateaus after a certain standard of living is achieved. In developed nations, baseline economic requirements were surpassed decades ago. Consequently, individuals increasingly prioritize factors that maximize life satisfaction and happiness. Wealth represents only one component of an individual’s overall life circumstances.

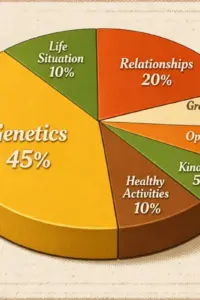
While genetics heavily influence baseline happiness, numerous controllable factors significantly impact personal well-being. Cultivating strong personal relationships, practicing gratitude, maintaining an optimistic outlook, and incorporating regular outdoor physical activity into daily routines consistently correlate with higher life satisfaction.
Despite the availability of these insights, pervasive background anxiety remains prevalent even among financially independent individuals. This persistent worry often stems from evolutionary biology. Human beings evolved as threat-detection organisms designed to navigate physical danger, scarcity, and social exclusion. When immediate physical survival threats are successfully resolved, the human brain frequently redirects its detection machinery toward abstract concerns, ranging from economic scarcity to social status, homeownership regulations, tax strategies, and required minimum distributions.

Confronting and Managing Financial Fear
Overcoming pervasive financial fear requires conscious self-awareness and rational evaluation. Examining personal history helps contextualize these anxieties. Feelings of financial scarcity or insecurity often trace back to childhood experiences or family dynamics shaped by generational hardships, such as the Great Depression. Similarly, individuals who have encountered trauma or chronic stress in their past frequently manifest heightened anxiety regarding future security, even when their objective financial position is secure.
Identifying the specific nature of a fear by examining worst-case scenarios often reveals that perceived catastrophes are manageable. Taking deliberate action against uncertainty replaces unfamiliarity with confidence. Developing resilience—the capacity to adapt to changing environments—neutralizes abstract dread.

Mitigating anxiety also involves curating one’s informational environment. Continuous exposure to sensationalized news media often amplifies fear by highlighting isolated worst-case scenarios. Shifting focus toward active problem-solving, physical well-being, outdoor activity, and positive social circles helps align daily life with human evolutionary needs. Engaging with optimistic, productive communities that prioritize living fulfilling lives rather than dwelling on speculative dangers fosters a healthier psychological outlook.
Approaching life’s transitions through the lens of experimentation reframes uncertainty. Whether evaluating career shifts, relocating, or entering retirement, viewing these milestones as controlled experiments reduces emotional friction.

This experimental mindset applies directly to the current artificial intelligence revolution. Rather than succumbing to speculative alarmism, examining the technological and economic foundations of AI reveals substantial potential upside alongside disruption. AI functions effectively as an advanced cognitive tool, enhancing operational efficiency, productivity, and broader economic prosperity.
Like previous technological shifts—such as the advent of the internet and mobile computing—automation inevitably displaces specific entry-level administrative and operational roles while simultaneously lowering service costs and catalyzing entirely new industries. While the economic gains of such innovations frequently concentrate among asset owners and shareholders, the underlying technology remains another tool within the broader arc of human productivity.

Ultimately, artificial intelligence represents an opportunity for deliberate choice. Individuals retain the agency to determine whether emerging technological shifts serve as catalysts for continuous learning, positive adaptation, and a more engaged life, or as sources of persistent apprehension.