In the specialized world of very early retirement, adherents frequently overlook one of the most foundational pillars relied upon by traditional retirees: the Social Security program. While the system serves as an essential safety net for the approximately 73 million current beneficiaries and provides critical income for those without alternative earnings, it often remains a distant abstraction for individuals leaving the workforce in their thirties and forties. For early retirees, the priority is securing immediate financial independence rather than planning for a government benefit decades away, coupled with a general reluctance to rely on long-term government promises.
This perspective is common among young retirees, but time progresses, and demographics shift. As early retirees age and observe peers entering traditional retirement age, questions surrounding Social Security inevitably surface, accompanied by a vast landscape of conflicting opinions and complex projections. However, a closer examination of the underlying math reveals that incorporating Social Security into a retirement strategy ultimately boils down to a single pivotal metric: the Net Present Value of a future lifetime stream of Social Security payments.

For someone retiring in their thirties, the present value of future Social Security benefits is negligible. Even assuming the program fulfills its obligations entirely, payouts remain decades away, requiring individuals to fund their entire living expenses independently for thirty years or more before eligibility begins. Conversely, individuals who delay retirement until their sixties, after decades of continuous contributions and with modest living expenses, may find that future Social Security payments entirely cover their needs. In this scenario, future benefits rise automatically with inflation, reducing or eliminating the necessity for additional personal savings.
Between these two extremes lies a dynamic middle ground. Rather than viewing Social Security as irrelevant until reaching eligibility age, retirees can treat future benefits as an asset that diminishes the volume of personal capital required to sustain retirement. Calculating this involves the Net Present Value formula, a financial concept that can be evaluated using standard spreadsheets, financial calculators, or artificial intelligence research tools without requiring manual calculation of complex equations.

To illustrate how this functions, consider a hypothetical young couple evaluating their financial standing at age thirty. Making reasonable baseline assumptions regarding future earnings and inflation, a thirty-year stream of future income yields a substantial initial figure when calculated at present value. Adjusting that total to account for the decades remaining before payments begin reveals a tangible present-day asset. Depositing that equivalent sum into an investment portfolio today and allowing it to compound over thirty-two years would generate a portfolio capable of funding decades of inflation-adjusted monthly income. Consequently, early retirees can account for this projected value within their net worth calculations, effectively reducing the capital they need to accumulate independently.
This principle applies across different age brackets and retirement timelines. For individuals closer to traditional retirement age, the Net Present Value of an imminent, long-term monthly benefit climbs significantly higher. If a sixty-two-year-old couple requires a specific monthly income stream lasting thirty years, the present value of those guaranteed, inflation-adjusted payments translates into a massive capital equivalent. If they were to self-fund that identical income stream through an investment portfolio alone, the required principal would be immense.

A more typical scenario involves older workers facing career disruptions or diminished savings who nevertheless wish to exit the workforce. Traditional financial advice often urges these workers to delay retirement until they reach full retirement age or later to maximize monthly Social Security payouts. However, analyzing these options through the lens of time value and investment returns reveals a different dynamic.
When workers begin collecting benefits at the earliest eligible age—such as sixty-two—and reinvest those payments into growth-oriented index funds, the compounding returns over subsequent years can eclipse the higher monthly payout achieved by delaying retirement. By the time a more patient peer begins drawing an increased monthly benefit years later, the early claimant has already accumulated a substantial investment balance. This head start often offsets the lower initial monthly payment.

For workers evaluating whether they can afford to leave their jobs early, the integration of projected Social Security benefits creates a stabilizing effect. Every additional year of part-time work or continued saving triggers a triple benefit: it increases future Social Security payouts, adds to personal investment capital, and reduces the total number of years that personal savings must sustain. Once the combined income from investment portfolios and projected Social Security reaches the household’s targeted monthly threshold, the transition to retirement becomes mathematically viable.
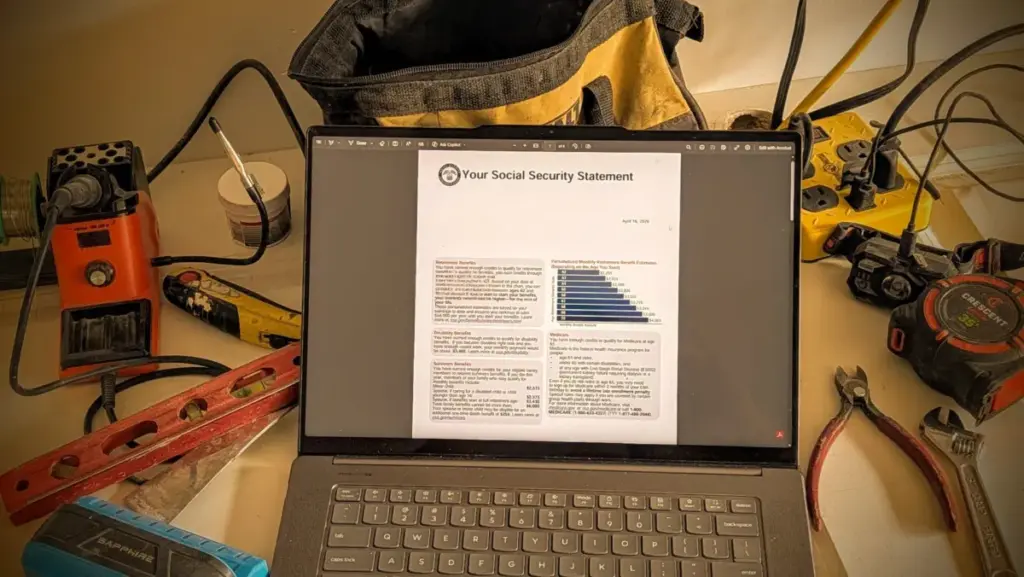
Evaluating these dynamics through standardized projections demonstrates that future benefits hold meaningful value even for middle-aged workers. While these figures do not represent extravagant wealth, they function as substantial financial boosts capable of covering major lifecycle expenses. Many individuals approach retirement without ever factoring these projected payments into their personal balance sheets, missing an opportunity to gauge their true financial security accurately.

Common concerns regarding the future of Social Security often center on the possibility of program reductions or policy changes. Given that retirees and aging voters represent a dominant demographic block, sweeping reductions remain politically challenging. Policy adjustments are more frequently projected to impact higher earners, meaning individuals who achieve substantial personal wealth may see modified benefits. For those in higher income brackets, such adjustments align with overall financial self-sufficiency.
Ultimately, understanding the mechanics of Social Security and utilizing analytical tools allows workers to evaluate their retirement readiness with greater clarity. By examining projected benefits through financial valuation methods, individuals can better assess their long-term security, manage financial anxiety, and make informed decisions regarding their timeline for leaving the workforce.