As the stock market continues to surprise observers by scaling record valuations, a familiar anxiety has gripped many investors. Buoyed by a frenzied boom in Artificial Intelligence, current market milestones have ignited widespread fears that an impending crash—potentially dwarfing the dot-com bust of the early 2000s—is just around the corner. For veterans of past financial cycles, these market jitters evoke memories of previous bubbles, yet financial commentators and long-term retirees suggest that the underlying panic may be rooted more in human psychology than economic reality.
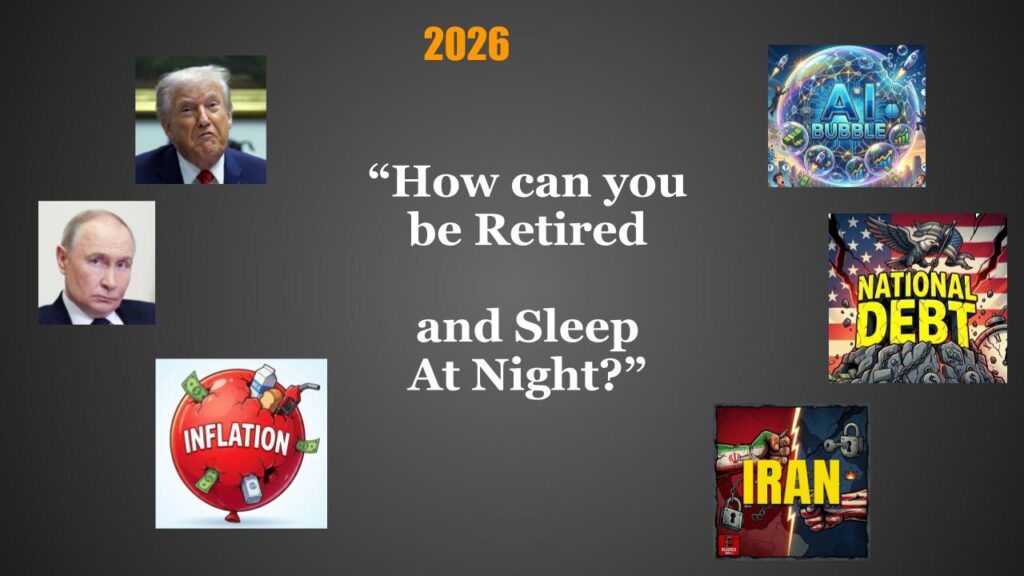
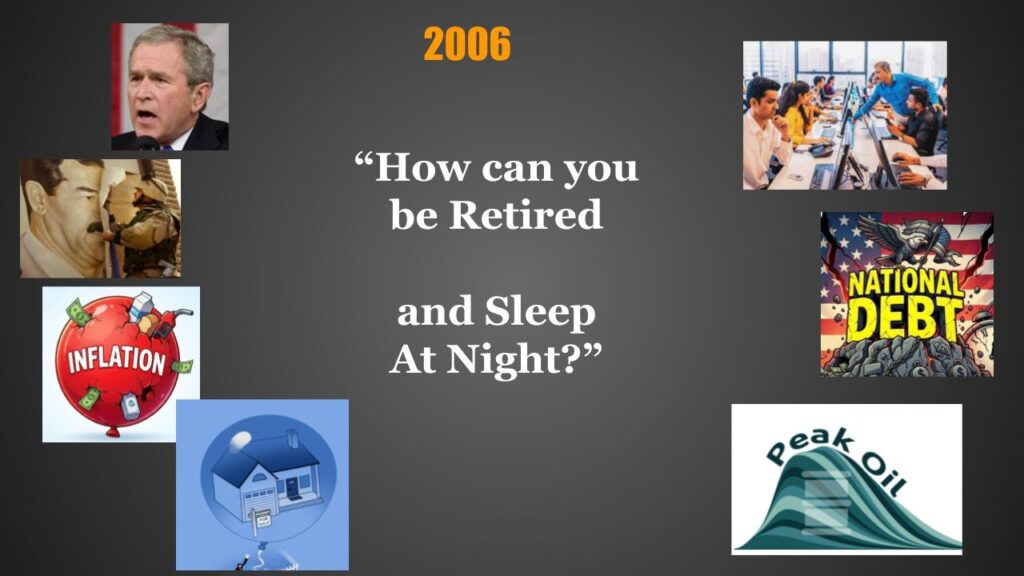
Examining the historical trajectory of global markets reveals that existential worry is a constant companion for investors. Looking back two decades to 2006, market participants faced a markedly different set of anxieties, including geopolitical conflicts in the Middle East, escalating national debt, inflation concerns, and a vastly overvalued housing market. At the time, economic commentators warned of an imminent collapse driven by the housing bubble, alongside widespread fears that job outsourcing to emerging economies like India and China would devastate domestic employment. There were even intense debates regarding "peak oil," with predictions that fossil fuel depletion would spell doom for global stability.
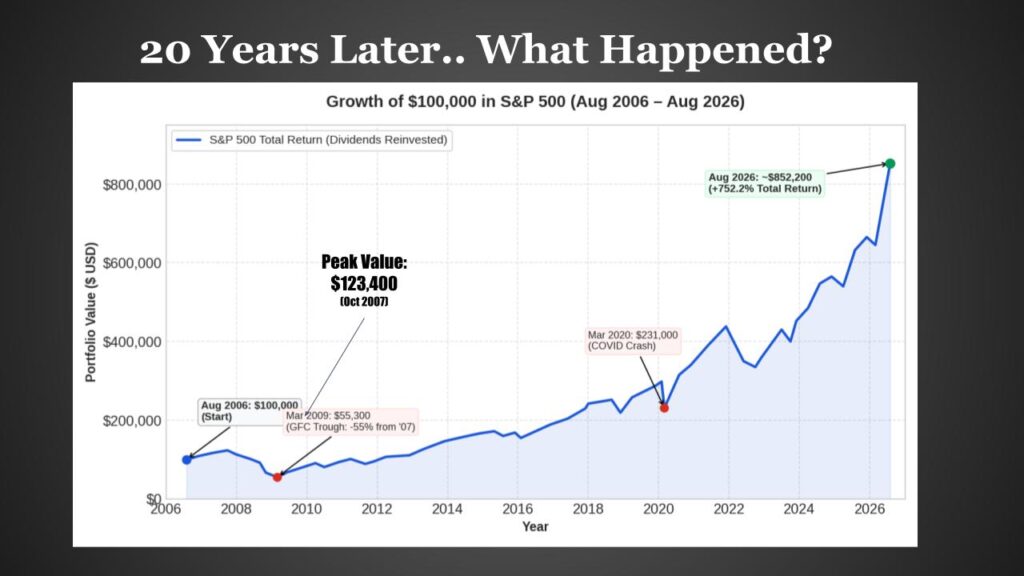
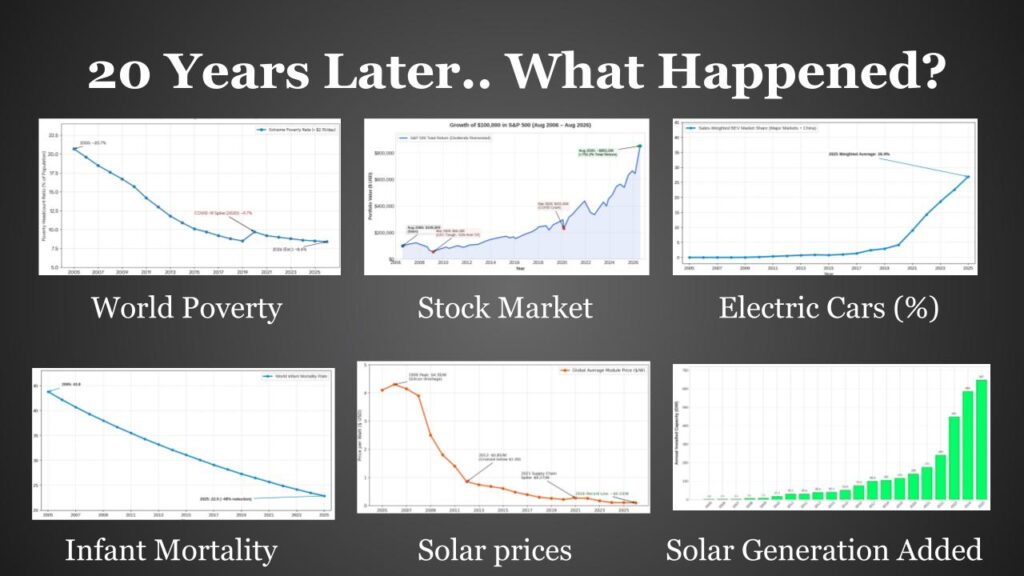
Despite those very real concerns, the subsequent twenty years saw substantial economic growth and technological advancement. Even the Great Financial Crisis—triggered by irrational exuberance in housing and complex financial leverage—ultimately proved to be a temporary setback in the broader scope of long-term market performance. Historical data shows that despite major downturns, including the 2008 financial collapse and the 2020 pandemic crash, diversified investments have historically yielded substantial long-term gains. Furthermore, global living standards improved dramatically over the same period, marked by a significant decline in extreme poverty, a halving of infant mortality rates, and exponential cost reductions in clean energy technologies like solar power.
Will the AI Bubble Ruin Our Retirement?
The central question facing modern investors is whether the current artificial intelligence boom represents a fundamentally different and more dangerous threat to retirement security. Skeptics point to towering national debt figures, geopolitical instability, and the sheer velocity of the AI market valuation as signs that traditional economic guardrails are failing. The financial media frequently amplifies these concerns, spinning intricate narratives about potential market destruction or technological displacement.
However, market historians and long-term financial independence advocates argue that such fears overlook the foundational driver of economic prosperity: productivity. At its core, the economy is not merely a collection of financial systems or computer-generated stock tickers, but a network of real people performing tangible work and developing practical inventions. The financial system itself is a human construct; if a market correction occurs because valuations become detached from reality, the underlying infrastructure of human ingenuity and productive capacity remains intact.
Historically, true economic growth and improvements in standard of living stem directly from productivity enhancements. When new technologies emerge, they invariably cause short-term disruption, displacing certain job categories while simultaneously laying the groundwork for entirely new industries. This dynamic mirrors the advent of the internet and the subsequent mobile revolution. While the financial rewards of such technological leaps often concentrate initially among corporate shareholders and business owners, the broader macroeconomic effect is an increase in efficiency and societal wealth.
Understanding Fear and Market Psychology
To understand why market volatility causes such acute distress, financial analysts often look past macroeconomic indicators and examine human evolutionary biology. Humans evolved as danger-detection machines, relying on background anxiety to protect themselves from physical threats, scarcity, and social exclusion. When tangible survival threats are successfully mitigated in modern society, this ancient detection machinery does not simply switch off; instead, it relocates, finding new outlets in financial uncertainty, tax strategy, and market valuations.
This perpetual shifting of concern explains why individuals who achieve financial stability often pivot to new worries, ranging from neighborhood property rules to the management of required minimum distributions in retirement. Psychologists note that this persistent apprehension is frequently fueled by a combination of personal history, past trauma, and a steady diet of sensationalized daily news. Because modern media outlets rely heavily on highlighting the most alarming developments of the day, news consumption frequently acts as a catalyst for unwarranted panic, encouraging individuals to focus on hypothetical worst-case scenarios rather than objective reality.
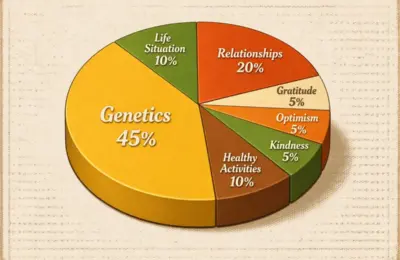
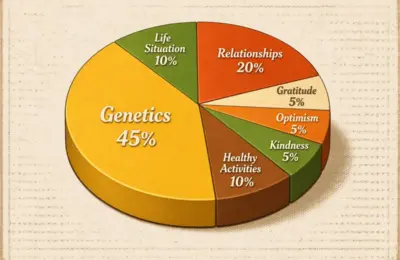
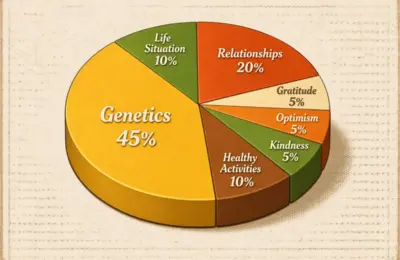
Experts suggest that combating this pervasive anxiety requires a deliberate shift in perspective. Rather than attempting to control unpredictable external systems like the stock market or global geopolitics, individuals can focus on modifying their daily behaviors, curating their information intake, and cultivating resilience. By treating major life transitions and economic shifts as manageable experiments rather than existential threats, investors can better process uncertainty without succumbing to reactionary fear.
Ultimately, whether evaluating the housing market of 2006 or the artificial intelligence landscape of today, market cycles remain an inherent feature of capitalist economies. While technological advancements will continue to disrupt traditional labor markets and reshape corporate landscapes, the fundamental capacity of human beings to adapt, innovate, and generate real economic value has consistently prevailed over past panics.