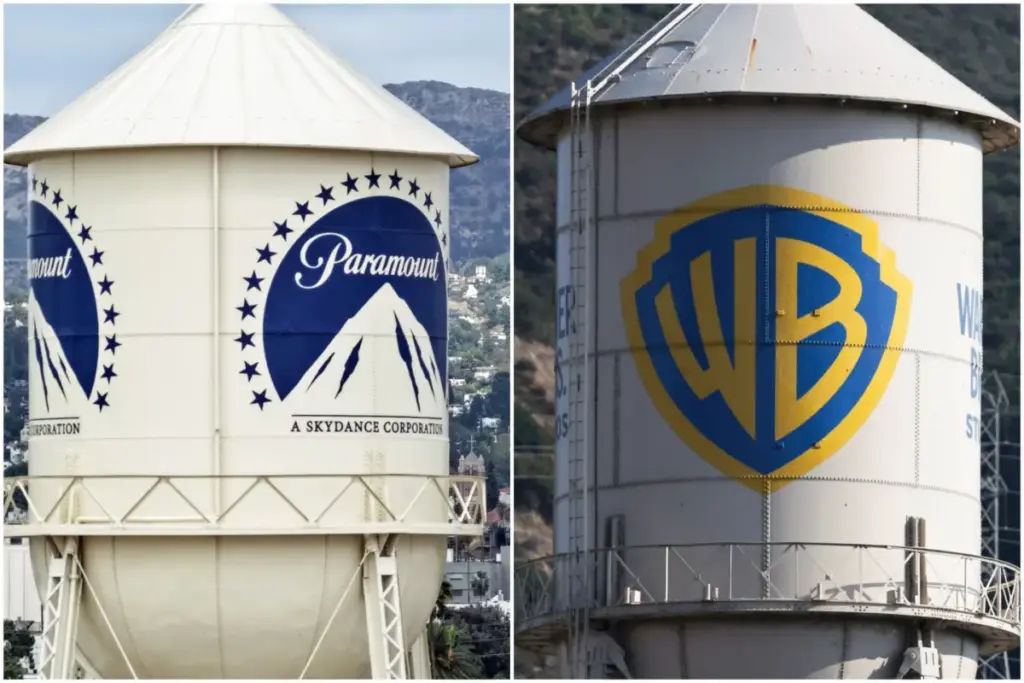
Paramount Skydance’s monumental $111 billion agreement to merge with Warner Bros. Discovery is rapidly approaching the finish line, though executives and investors alike acknowledge that the massive media consolidation is not quite a done deal just yet. Even as final regulatory reviews wind their way through the legal system and corporate logistics are put into motion, the company is actively preparing for the transaction to officially close within the next few weeks, marking one of the most transformative combinations in the modern history of the entertainment and media industry.
In a clear sign that corporate leadership anticipates the merger crossing the threshold shortly, Paramount formally notified the Securities and Exchange Commission in a filing on Friday regarding significant shifts in its public market presence. According to the regulatory disclosure, the company’s board of directors made the determination on September 25 to voluntarily withdraw the listing of its Class B common stock from the Nasdaq Global Select Market. The shares, which have traded under the ticker symbol "PSKY," will be transferred over to the New York Stock Exchange.
The corporate transition timetable outlines that the listing and active trading of Paramount’s Class B Common Stock on Nasdaq is expected to end at market close on or about October 5. Immediately following that shift, trading of the stock is slated to resume on the floor of the NYSE at market open on or about October 6.
Alongside the exchange transition, the Paramount board has established a specific record date for a previously announced corporate maneuver. The close of business on October 5 has been set as the record date for the distribution of warrants, which will provide eligible holders with the option to purchase additional shares of Class B Common Stock directly on the NYSE. Under the current schedule, those newly accessible shares would begin trading on October 13.
However, corporate leadership has emphasized that these financial mechanisms are entirely contingent on the ultimate success of the broader transaction. Paramount explicitly noted in its filings that the distribution of the warrants is strictly tied to the closing of the previously announced acquisition of Warner Bros. Discovery. Because the multi-billion-dollar merger remains subject to final closing conditions, the absolute timing for the ultimate completion of the WBD transaction remains fluid and uncertain.
Because of this inherent timeline uncertainty, Paramount has built necessary operational flexibility into its corporate planning. The company retains the administrative right to cancel the established record date and issue date entirely, or alternatively, to postpone the record date and issue date to a later point in time should the merger closing timeline shift.
The path toward this monumental consolidation has navigated a labyrinth of regulatory challenges, with the final major legal hurdle clearing earlier this week. Paramount reached a definitive settlement with a coalition of 12 Democratic state attorneys general who had previously banded together to file an antitrust lawsuit aimed at blocking the merger entirely. While the proposed settlement must still receive formal approval from the presiding court—which would result in the dismissal of the states’ blocking lawsuit—the agreement notably does not require major structural concessions from Paramount.
Despite the breakthrough with the state attorneys general, the judicial review process remains active. The judge presiding over the case is currently reviewing the proposed settlement terms and has requested that the involved parties file a formal response by Monday, September 28. This judicial inquiry follows a specific request submitted by Senator Cory Booker, a Democrat from New Jersey, who has urged the court to launch an independent review of the proposed consent decree before giving the final judicial sign-off.
Time is increasingly of the essence for both media giants as the calendar turns toward a critical financial threshold. Starting on October 1, Paramount will begin accruing a substantial financial penalty known as a "ticking fee." This fee, valued at $7 million per day, will be payable directly to Warner Bros. Discovery shareholders for every day that the merger remains unclosed, thereby adding financial urgency to the finalization of the remaining closing steps.
The warrants that Paramount intends to distribute to existing PSKY shareholders are strategically designed to provide eligible holders of its Class B Common Stock with a unique market opportunity. Specifically, the warrants offer the chance to purchase shares of Class B Common Stock in a newly formed entity under terms that closely mirror those offered to the powerful equity syndicate backing the Warner Bros. Discovery acquisition. This elite backing syndicate prominently includes media executive David Ellison, his father and technology billionaire Larry Ellison, and Gerry Cardinale, the head of RedBird Capital Partners.
Current corporate projections indicate that the company expects to issue approximately 470 million warrants on October 5. In a structural carve-out for institutional employee benefit vehicles, shares of Class B Common Stock that are currently held directly by the Paramount Global 401(k) Plan and the Paramount Global Master Trust will bypass the warrant distribution process entirely. Instead of receiving warrants, these retirement and master trust accounts will receive direct allocations of Class B Common Stock.
Should the warrants successfully be issued according to the planned schedule, each individual warrant will initially entitle the verified holder to purchase one share of Class B Common Stock. The initial exercise price per share will be calculated based on the average of the daily volume-weighted average price of the Class B Common Stock evaluated across a 20-trading-day window. This calculation period concludes on, and includes, the third business day prior to the official closing date of the Warner Bros. Discovery merger.
Furthermore, to protect both the issuing entity and the participating investors against extreme market volatility, the purchase price for the warrants has been bound by structural guardrails. The final price is subject to a strict maximum cap of $16.02 per share, alongside a protected minimum floor of $12.00 per share. As Paramount management and legal teams monitor the remaining judicial reviews and market preparations, the media landscape stands on the precipice of a historic union, awaiting the final clearances that will bring the multi-billion-dollar corporate marriage to completion.