Spending on video content across seven major markets in Asia is projected to reach $15.1 billion by 2026, according to a comprehensive new study released by Media Partners Asia (MPA). Titled “Asia Video Content Dynamics 2026,” the report highlights a structural transformation across the region’s entertainment landscape, characterized by shrinking traditional television budgets and a decisive capital shift toward streaming platforms and local cinematic productions.
The MPA study closely examines the media ecosystems of India, Indonesia, South Korea, Malaysia, the Philippines, Thailand, and Vietnam. Across these seven territories, total content spending stood at an estimated $14.8 billion in 2025 and is forecasted to climb to $15.4 billion by 2031.
Despite the rapid ascendance of digital platforms, traditional television still maintains a significant footprint, capturing roughly 60% of total video content investment. Online video accounts for approximately 30%, while theatrical film production represents the remaining 10%. Geographic concentration remains pronounced; South Korea, with $6.9 billion in investments, and India, with $5 billion, together accounted for roughly 80% of total content spending in 2025.
Industry analysts emphasize that this shift reflects changing consumer habits rather than a contraction of the overall market. “The viewership data shows demand is intact,” said Myat Pan Phyu, an analyst at MPA. “Premium VOD engagement continues to grow across India, Korea and Southeast Asia, streaming now leads content investment in India, and local stories are winning at the box office from Hanoi to Jakarta and Mumbai. This is a story of reallocation rather than retreat as capital moves toward streaming and local film, where both audiences and returns are growing.”
Profitability Challenges and Strategic Reallocation
Despite robust audience engagement and an abundance of creative talent across the region, the financial picture for traditional media businesses remains complex. The MPA report notes that strong audience reach is not reliably converting into healthy profit margins. Consequently, many long-established media companies continue to trade well below their equity book value.
To build long-term value in this shifting environment, MPA suggests that firms must spend capital prudently, aggressively trim operational costs, and defend the core content that genuinely sets them apart from competitors.
India’s Digital Watershed and Streaming Dominance
India reached a major milestone last year, marking a structural turning point for the country’s media sector. In 2025, online video captured 46% of India’s total content investment, narrowly edging past traditional television at 42% and seizing the market lead for the first time in history. Indian consumers demonstrated an insatiable appetite for digital content, logging a staggering 420 billion hours of online video over the course of the year.
Among digital platforms, JioHotstar has established a dominant market position, commanding a 58% share of premium subscription video-on-demand (SVOD) viewing in the country while supporting a user base of more than 180 million paying subscribers.
Similar trends are unfolding across other key Asian territories. In South Korea, TVING has solidified its status as a clear runner-up behind global giant Netflix. Meanwhile, Indonesian streaming platform Vidio has maintained its leadership position in its home market with more than 6 million paying subscribers, achieving a significant financial milestone by turning EBITDA-positive since the fourth quarter of 2025.
The Decisive Role of Sports Rights
According to the MPA report, live sports rights have emerged as a primary differentiator for streaming platforms looking to capture and retain subscribers.
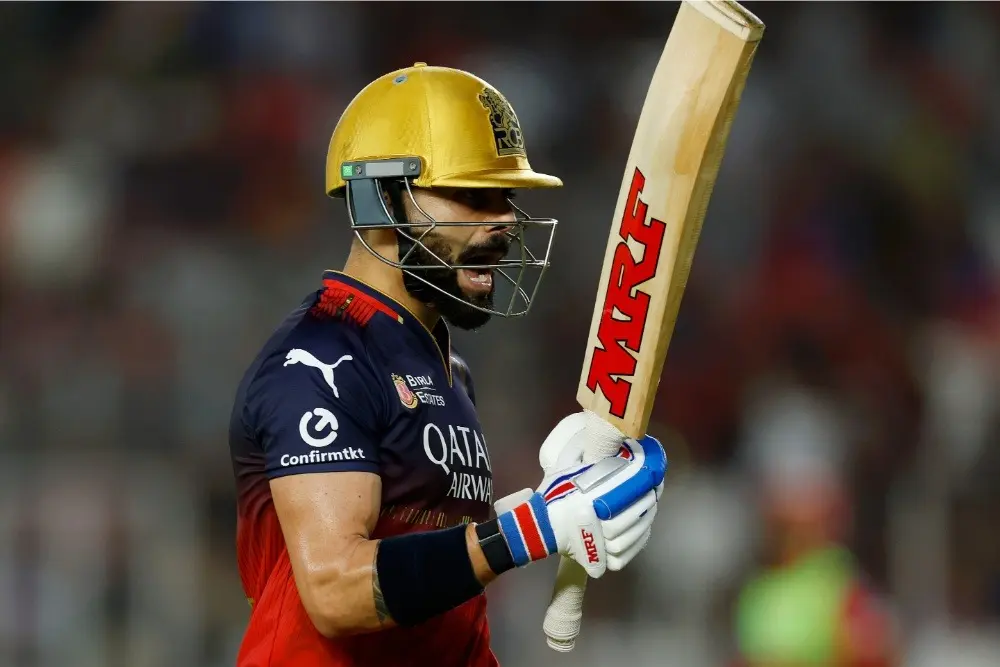
In India, cricket played a vital role in driving up JioHotstar’s connected-TV reach by 26% during the 2026 Indian Premier League tournament. In South Korea, exclusive broadcasting rights for KBO baseball propelled TVING’s subscriber base from 5.3 million to 6.5 million. Simultaneously, Coupang Play has successfully cultivated the widest portfolio of premium sports offerings in the Korean market.
In Southeast Asia, platforms are utilizing live sports to bolster engagement across various pricing tiers. Vidio integrates Indonesian football leagues alongside the UEFA Champions League and the Premier League into its service offerings. In Vietnam, broadcasts of the FIFA World Cup provided a major catalyst, lifting premium VOD viewing figures by 22% over the course of the year.
The Theatrical Resurgence of Local Film
Local film production stands out in the report as one of the clearest and most dynamic opportunities for growth across the region. Box office revenues rebounded strongly, driven heavily by home-grown narratives that resonated deeply with domestic audiences.
In Vietnam, total box office earnings grew by 20% to reach $213 million in 2025, with homegrown cinematic titles capturing an impressive 69% of total ticket receipts. Indonesia experienced a similar trajectory, seeing its box office rise 10.5% to $325 million, where local films accounted for 60% of the market share. India achieved a historic box office milestone, generating a record $1.41 billion. Meanwhile, South Korea is experiencing a substantial theatrical recovery in 2026, fueled by a strengthened lineup of domestic releases.
Television and Production Squeeze
In contrast to the rapid growth of streaming and local cinema, traditional television faces mounting headwinds. While audience viewership remains steady, traditional revenue streams continue to contract. Thai TV advertising revenues fell by 18% to $422 million in 2025, and MPA warns that several regional markets are currently carrying an excess of broadcast capacity that cannot be sustained by current advertising income.
Independent producers are also feeling the pressure. Broadcasters and streaming services have grown increasingly selective regarding the content they commission, directly impacting production houses that rely heavily on baseline production fees. Value in the production sector is shifting rapidly toward integrated studios and creators who own their intellectual property, maintain repeat buyers, or generate revenue from multiple distribution streams.
Production costs vary significantly across the region. South Korea remains the most expensive place to produce content in Asia, with drama profit margins compressed to between 5% and 10%. While production costs are lower in Southeast Asia, tighter commissioning practices from buyers are similarly impacting local producers there.
Industry Consolidation and the Path Forward
“Asia’s video industries are not short of audiences or creative capability. They are short of structures that convert both into sustainable returns,” said Stephen Laslocky, vice president at MPA. “As the margin for error narrows, management quality will become decisive. Companies that rationalize legacy costs through restructuring and the adoption of new technologies such as AI, collaborate where independent investment no longer makes sense and protect the content that gives viewers a reason to stay will increasingly outperform, and the valuation gap between winners and losers will widen.”
Among the seven surveyed markets, MPA identifies India and Korea as the most advanced in terms of industry consolidation. India set the pace for major market realignment through the landmark 2024 merger of Reliance’s Viacom18 and Disney’s Star India to form JioStar, opening the door for potential future mergers and acquisitions. In South Korea, industry stakeholders are closely watching the proposed combination of TVING and Wavve to unlock commercial value. While Southeast Asia has historically lagged in consolidation, the report highlights clear potential for future collaboration and market rationalization across the Philippines, Thailand, and Indonesia.
Additionally, MPA estimates that strategically reorganizing major regional players—such as splitting CJ ENM into four clearly defined business units—could unlock an equity valuation significantly higher than the company’s current market capitalization.