By Staff Reporters
For decades, the stock market has continued to surprise investors, oscillating between nerve-wracking crashes that erode retirement portfolios and unprecedented bull runs that reach super-charged valuations. In the current economic landscape, the meteoric rise of Artificial Intelligence has sparked a familiar sense of market frenzy. While some investors enjoy record-high portfolios, many worry that this boom is merely a precursor to an inevitable market collapse—potentially echoing the devastating dot-com crash of the early 2000s.
Addressing these widespread anxieties, veteran financial commentator and early retirement pioneer Mr. Money Mustache recently shared insights from a new presentation delivered at Camp FI Midwest, with plans for an expanded address at the upcoming Bogleheads conference in November. Drawing on over two decades of personal experience in early retirement, he argues that while market volatility and technological shifts are real, the pervasive panic surrounding the AI bubble stems less from actual economic doom and more from a fundamental human predisposition toward fear.
Will the AI Bubble Ruin Our Retirement?
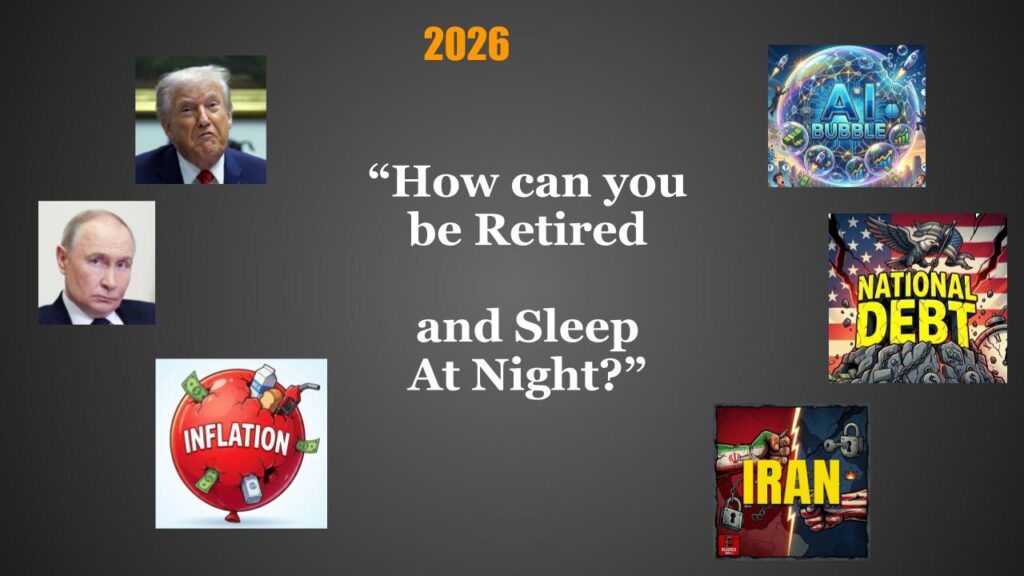
Reflecting on his twenty-one years of early retirement, the financial commentator noted a recurring question from anxious peers: how one can remain comfortable and sleep soundly amid global instability, inflation, rising national debt, geopolitical conflicts, and the looming threat of an AI market correction.
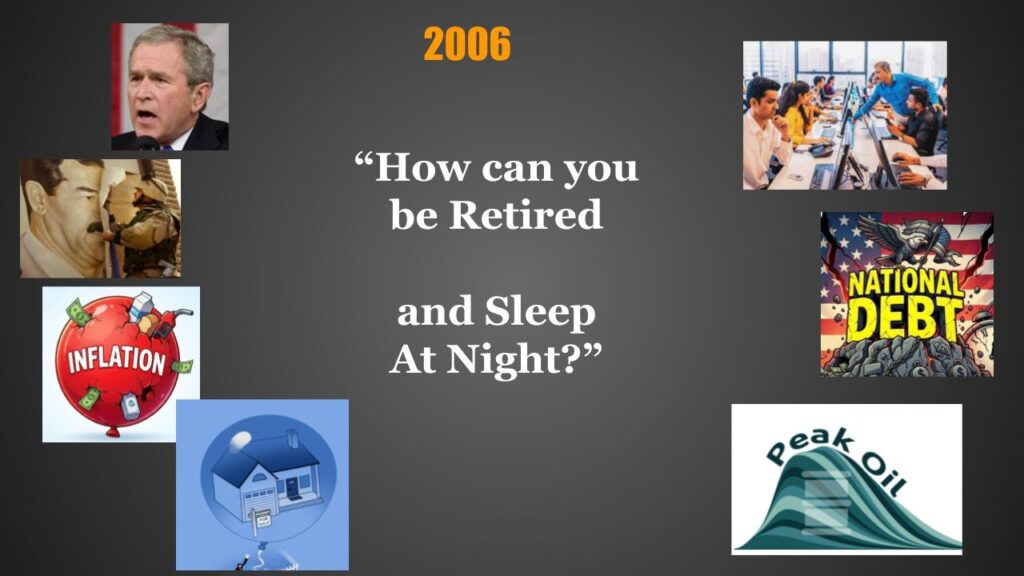
Curiously, these exact concerns are far from novel. Drawing a historical parallel, he pointed back to worries from 2006—over twenty years ago—when investors wrestled with a similarly turbulent news cycle. Back then, public anxiety centered around geopolitical leaders, wars in the Middle East, escalating national debt, rampant inflation, outsourcing concerns regarding India and China, and peak oil debates. At the time, the overarching fear was tied to the impending housing bubble rather than artificial intelligence.
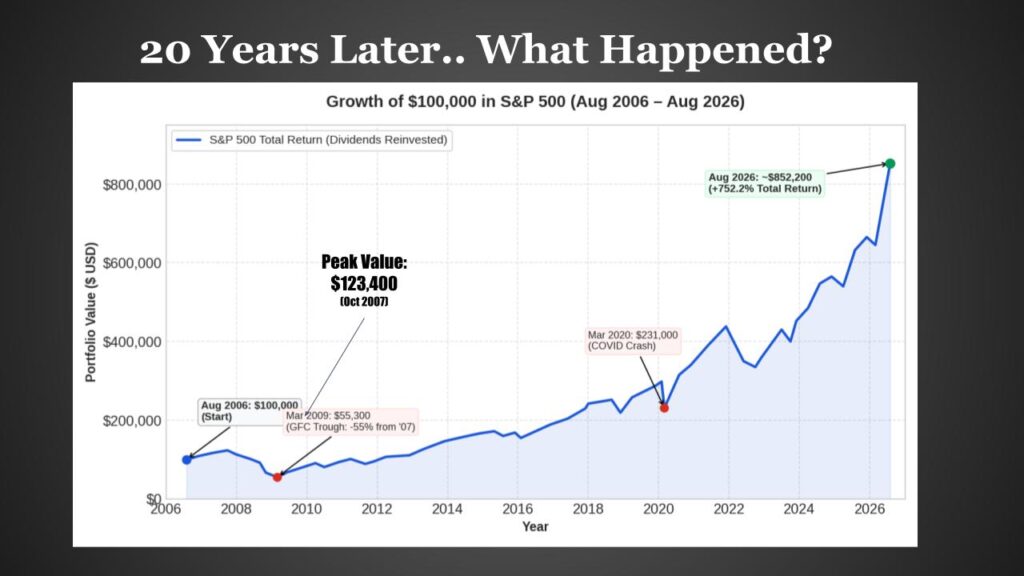
Despite the subsequent Great Financial Crisis—the most severe economic downturn since the Great Depression—long-term market data reveals a striking reality. An initial $100,000 investment made during those turbulent mid-2000 years would have grown significantly over the following two decades, easily absorbing subsequent disruptions such as the 2020 pandemic crash.
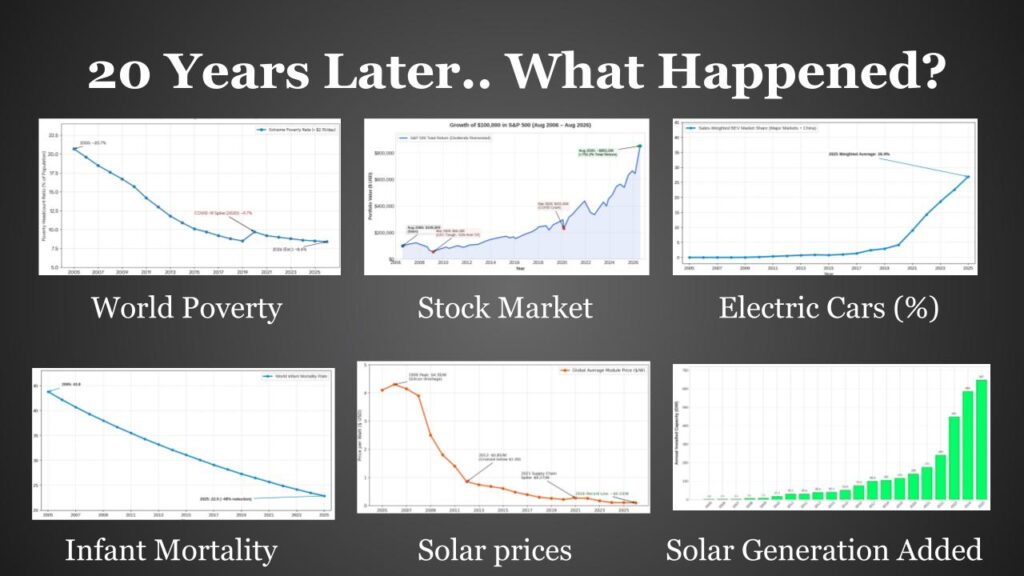
Beyond financial markets, global living standards advanced dramatically over the same twenty-year period. The proportion of the global population living in extreme poverty dropped from 20 percent to just 8 percent, while global infant mortality rates were cut in half. At the same time, clean energy adoption surged, driven by solar panels becoming roughly forty times cheaper and accounting for the vast majority of new energy generation capacity. Meanwhile, electric vehicle adoption expanded from negligible numbers to roughly a quarter of all global car sales.
Prosperity Comes From Productivity
Skeptics frequently question whether "this time is different," pointing to soaring US national debts or the unprecedented scale of artificial intelligence. Financial media outlets regularly amplify these fears, predicting catastrophic outcomes for unprepared retirees.
However, this narrative overlooks a fundamental economic principle: true prosperity is rooted in productivity rather than financial systems, which are ultimately human-made constructs represented by numbers on computer screens. When financial systems experience severe corrections, societies routinely restructure the underlying accounting and resume productive labor, much as they did following the 2008 financial crisis.
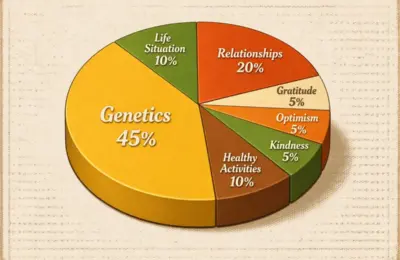
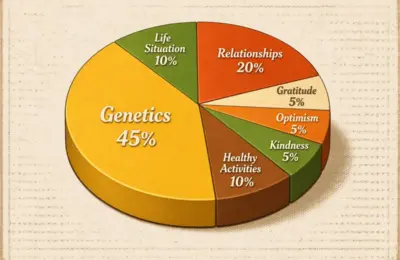
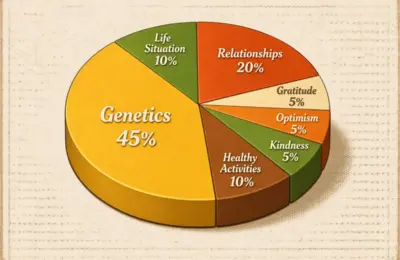
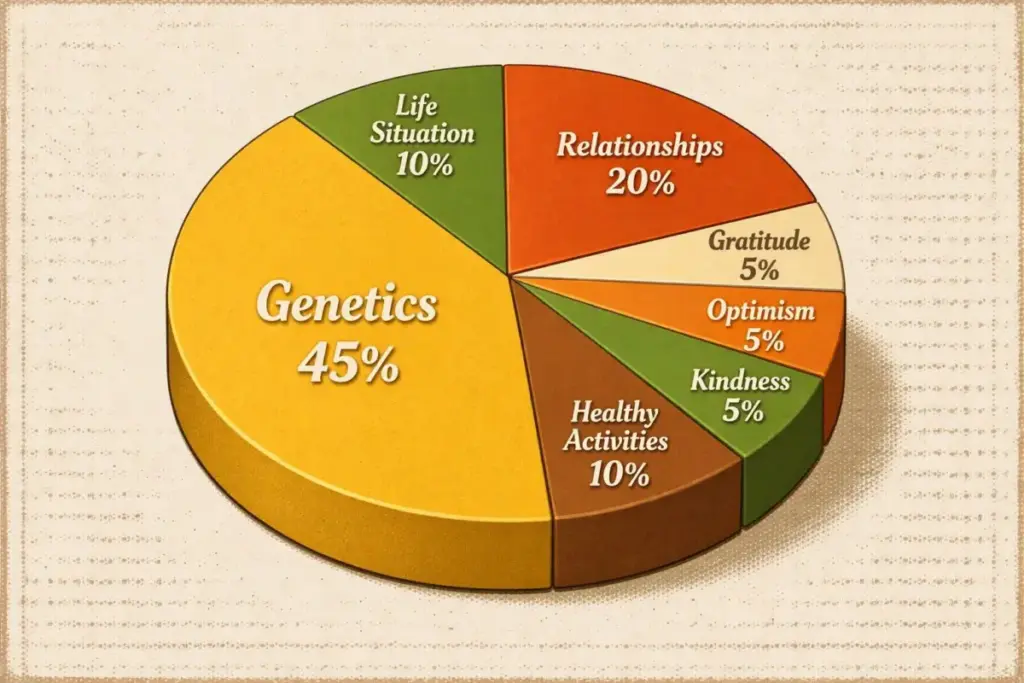
High productivity fuels standard of living improvements, economic growth, and the feasibility of early retirement. Yet, beyond a certain baseline required to meet modern living standards in developed nations, incremental wealth contributes minimally to overall human happiness. According to psychological and happiness frameworks, well-being is predominantly influenced by genetics, strong personal relationships, kindness, optimism, gratitude, and active outdoor lifestyles, with financial wealth playing a relatively minor role.
Understanding and Combating Fear
The persistence of financial anxiety despite objective historical growth highlights a deeper psychological phenomenon. Human beings evolved primarily as danger-detection machines. In primitive environments, this trait ensured survival against predators and disease. However, once immediate physical survival needs are met, the human brain continues scanning for threats, shifting from scarcity and social exclusion to investment strategies, tax planning, and regulatory mandates like Required Minimum Distributions.
Combatting this pervasive background fear requires self-awareness and rational evaluation. Examining personal history—such as childhood experiences shaped by parental scarcity or trauma—often sheds light on the root causes of financial anxiety. By identifying specific fears and imagining worst-case scenarios, individuals frequently realize that potential outcomes are far less catastrophic than anticipated.
Taking deliberate action is widely recognized as one of the most effective antidotes to fear. Engaging directly with unfamiliar situations builds confidence and resilience, transforming perceived threats into manageable challenges. Furthermore, curating one’s information diet by reducing reliance on sensationalized daily news—which disproportionately highlights alarming stories—and fostering connections with optimistic, action-oriented communities can dramatically alter one’s outlook.
Viewing AI Through the Lens of Experimentation
Approaching life’s transitions through the framework of experimentation can help reframe unfamiliar developments. Whether applied to minor lifestyle changes or significant milestones like career shifts and early retirement, treating changes as temporary experiments removes much of the emotional weight associated with uncertainty.
This experimental mindset applies directly to the current artificial intelligence boom. Rather than succumbing to doom-scrolling and apprehension, viewing AI as a sophisticated cognitive tool provides a clearer perspective. Much like a cognitive nail gun, AI functions as a powerful efficiency amplifier, boosting productivity and long-term societal prosperity.
While technological revolutions inevitably displace certain entry-level office and driving roles, historical precedent demonstrates that such shifts simultaneously reduce service costs and give rise to entirely new industries, mirroring the transformative impact of the internet and mobile smartphones. Although the economic rewards of these innovations initially concentrate among capital owners and shareholders—including everyday investors with diversified portfolios—artificial intelligence ultimately presents individuals with a choice: to view technological advancement with fear, or to utilize it as a catalyst for continuous learning, adaptation, and personal growth.